


















Huawei is cancelling Moore’s law
How sanctions accelerate technology
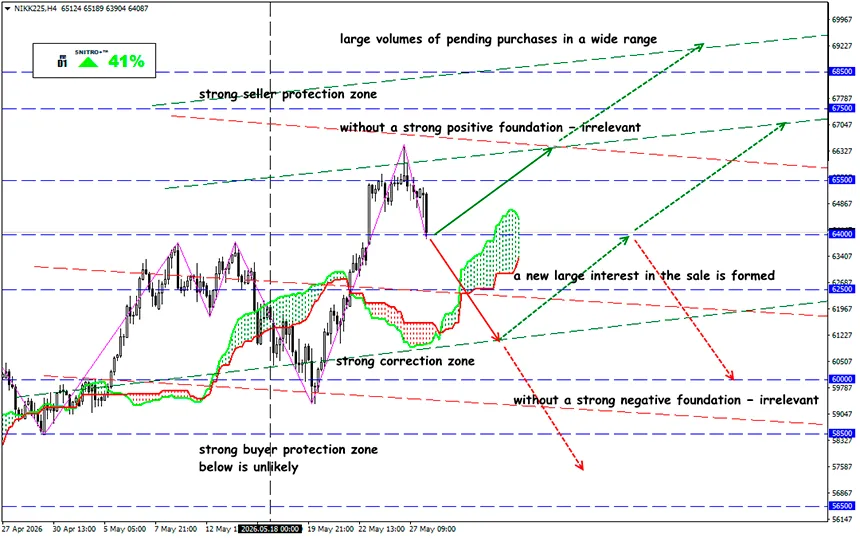
NIKK225
Key zone: 64,000 -65,000
Buy: 65,500 (on strong positive fundamentals); target 67,500; StopLoss 65,000
Sell: 63,500 (on a confident break above 64,000); target 61,500; StopLoss 64,000
When the usual route is unavailable, people search for alternative paths — and sometimes those paths become the new standard. For several decades, the semiconductor industry has lived according to Moore’s Law: the smaller the transistors, the more powerful the chip. But U.S. sanctions deprived China of access to products from the Dutch company ASML — specifically its EUV lithography systems, which are required for manufacturing modern chips.
Catching up with TSMC and Samsung through the traditional scenario became practically impossible. And then the revolution happened — Huawei introduced the Tau Scaling concept and the LogicFolding architecture.
Tau Scaling proposes replacing geometric scaling with temporal scaling. Instead of competing for the smallest transistor size, Huawei proposes optimizing the speed of signal transmission through the chip architecture. The practical implementation of the idea became LogicFolding — a system of vertical arrangement of computing blocks with reduced lengths of critical interconnections.
Huawei claims that such a scheme already provides a 53.5–55% increase in transistor density, a 41% improvement in energy efficiency, and frequency growth up to 3.1 GHz; however, there has not yet been an independent audit of these figures. Therefore, the current market effect is more a reassessment of future expectations than confirmation of actual technical superiority.
Let us recall:
For the market, this is not simply another engineering development, but an attempt by China to change economics and redistribute capital within the Asian technology sector. Huawei is trying to turn this idea into the main driver of performance. This fundamentally changes the sector’s investment logic. If successful, the market may begin reassessing companies and the roles of leaders in lithographic manufacturing.
- The main potential beneficiaries of such a scenario are SMIC, which gains a chance to manufacture more competitive chips without EUV, manufacturers of equipment for chip packaging and interconnects, as well as Huawei itself with the Kirin and Ascend product lines.
- Competitors — Intel, TSMC, and AMD — are already actively investing in 3D packaging and hybrid chip interconnects.
- The market immediately captured the signal. Following Huawei’s presentation, SMIC shares rose approximately 7.6%, as investors saw an opportunity to reduce the technological gap without access to EUV. This is especially important for SMIC: the company is limited to mature process technologies, but with successful LogicFolding development it may be able to produce more competitive solutions.
- Positive prospects are emerging for Asian manufacturers of advanced packaging equipment and suppliers of materials for interlayer interconnects. The HBM memory segment appears particularly interesting, where Samsung Electronics and SK Hynix dominate.
- For the Taiwan market, the situation looks mixed. On the one hand, TSMC still maintains a massive technological lead and continues moving toward true 1.4-nm process technologies. But the very appearance of an alternative architectural model reduces the monopoly value of access to advanced lithography.
And what is the result?
Sanctions that were supposed to slow the development of China’s semiconductor sector are beginning to stimulate the search for alternative architectural solutions. Historically, it is precisely such periods of restrictions that often lead to shifts in technological cycles.
For Nvidia, the situation is also ambiguous. Huawei directly states its intention to scale LogicFolding for the Ascend AI product line by 2030, creating a local alternative to American GPUs. If China succeeds in partially reducing the gap in AI accelerators, this could affect Nvidia’s long-term valuations in the Asian region.
Right now, what matters is not so much Huawei itself, but the potential redistribution of capital within the entire Asian semiconductor sector. However, for now, markets are trading expectations rather than proven results.
So we act wisely and avoid unnecessary risks.
Profits to y’all!


